A payment is a donation when the giver expects nothing of real value back, and it is a sponsorship when the payer receives benefits the IRS treats as a “substantial return benefit.” That single distinction, drawn from IRS Publication 526 and the agency’s sponsorship guidance, controls whether a payment is deductible, taxable to the recipient, or something in between. Two specific dollar thresholds are important for tax obligations: a moderate threshold triggers a quid-pro-quo disclosure requirement, and a higher threshold triggers the written acknowledgment a donor needs to claim a deduction.
TL;DR:
- Sponsorship payments are tax-deductible only if they include no promotional language, endorsements, or exclusivity clauses that create a substantial return benefit.
- Payments exceeding the fair market value of received goods or services are partially deductible, with the excess amount representing the contribution.
- The $75 and $250 thresholds determine disclosure and acknowledgment requirements, and mixing these rules can lead to compliance errors.
- Clear contract language that separates acknowledgment from promotional elements helps preserve tax benefits and avoid unrelated business income tax exposure.
- Structuring sponsorships around employee activity, like Charity Miles’ program, allows for recognition while maintaining the donation-like tax treatment.
Table of Contents
- Donation and qualified sponsorship payment, defined
- How tax treatment splits between donors and nonprofits
- Applying the $75 and $250 thresholds correctly
- A quick way to classify any payment
- Weighing visibility against tax simplicity
- How Charity Miles structures employer sponsorship around movement
- Why the label on the check matters less than the deliverables
- FAQ
- Sources
Donation and qualified sponsorship payment, defined
A charitable contribution, under Publication 526, is a voluntary gift to a qualified organization made without getting or expecting anything of equal value in return. You write a check to a food bank, you get a thank-you letter, and that is the whole transaction. No goods, no services, no logo placement, no strings.
A qualified sponsorship payment works differently. The IRS defines it as money, property, or services given with no arrangement or expectation of a substantial return benefit beyond the use or acknowledgment of the sponsor’s name, logo, or product lines, according to the agency’s sponsorship guidance. Two quick examples show the line:
- A donor gives $500 to a local animal shelter and receives only a receipt: this is a straightforward donation.
- A company pays $5,000 to have its name listed as a 5K race sponsor, with no promotional copy or calls to action attached: this generally qualifies as a sponsorship acknowledgment, not advertising.
The difference between “our name appears on a banner” and “our name appears next to a discount code and a slogan” is the difference between acknowledgment and advertising, and it changes the tax outcome entirely.
How tax treatment splits between donors and nonprofits
Donor deductibility starts with giving to a qualified organization, and it depends on keeping records that match what you gave. Publication 526 sets dollar limits based on your adjusted gross income and the type of property donated, and it requires documentation scaled to the size of the gift. For charities, the question runs in the opposite direction: does accepting a sponsorship payment create unrelated business income tax exposure?
Under IRC §513(i), qualified sponsorship payments are not subject to UBIT. The moment a sponsorship agreement promises something beyond neutral acknowledgment, that protection can fail. Promotional language, price comparisons, and endorsements push a payment toward advertising, and advertising income is evaluated under general UBIT rules rather than the sponsorship safe harbor.
- A sponsor whose name appears alongside a logo and a general description of its product is typically still in acknowledgment territory.
- A sponsor whose message includes a qualitative claim, a price, or a call to action has likely crossed into advertising.
- Exclusivity clauses, discussed in the IRS’s exclusive-provider guidance, often count as a substantial return benefit on their own.
A payment exceeds the fair market value of received goods or services by the deductible portion; for example, when paying more than the value of a concert ticket, the excess amount is the deductible portion. The IRS quid-pro-quo rules use this exact example to show that only the amount exceeding the fair market value of what you received counts as a charitable gift. The same math applies whether the benefit is a ticket, a meal, or a sponsor’s premium booth space: value received gets subtracted first.
Applying the $75 and $250 thresholds correctly
Two separate dollar amounts govern two separate obligations, and mixing them up is a common and avoidable error.
- The $75 rule requires a charity to give the donor a written disclosure whenever a single payment exceeds $75 and is partly a contribution, partly a payment for goods or services, per the IRS quid-pro-quo guidance.
- The $250 rule requires the donor to hold a contemporaneous written acknowledgment for any single contribution of $250 or more before claiming it on a tax return, as stated in the IRS’s substantiation guidance.
- A simple thank-you note without the required elements, such as a description of the gift and any value received, does not satisfy either rule on its own.
The pattern holds regardless of the cause or the donor: calculate fair market value first, then apply whichever threshold the payment size triggers.
A quick way to classify any payment
Before a check gets written or an invoice gets issued, run the payment through a short set of questions.
- Does the agreement include a promotional call to action, like “visit our store” or “use code SAVE20”?
- Does it mention a price, an endorsement, or a comparative claim about the sponsor’s product?
- Does the sponsor get exclusivity, such as being named the only provider in its category?
- Is every benefit promised limited to use or acknowledgment of the sponsor’s name and logo?
Contract language settles most disputes before they start. Clauses granting exclusive-provider status, paid activations, or endorsement rights are the clearest signals of a substantial return benefit, and the IRS exclusive-provider guidance treats identical dollar amounts differently depending on whether those rights are attached. Nonprofits can protect the deductible or UBIT-exempt portion by separately pricing any promotional add-ons in the agreement, so the acknowledgment piece stays clean.
Pro Tip: Ask the nonprofit to itemize the fair market value of every benefit in writing before the payment is made, not after.
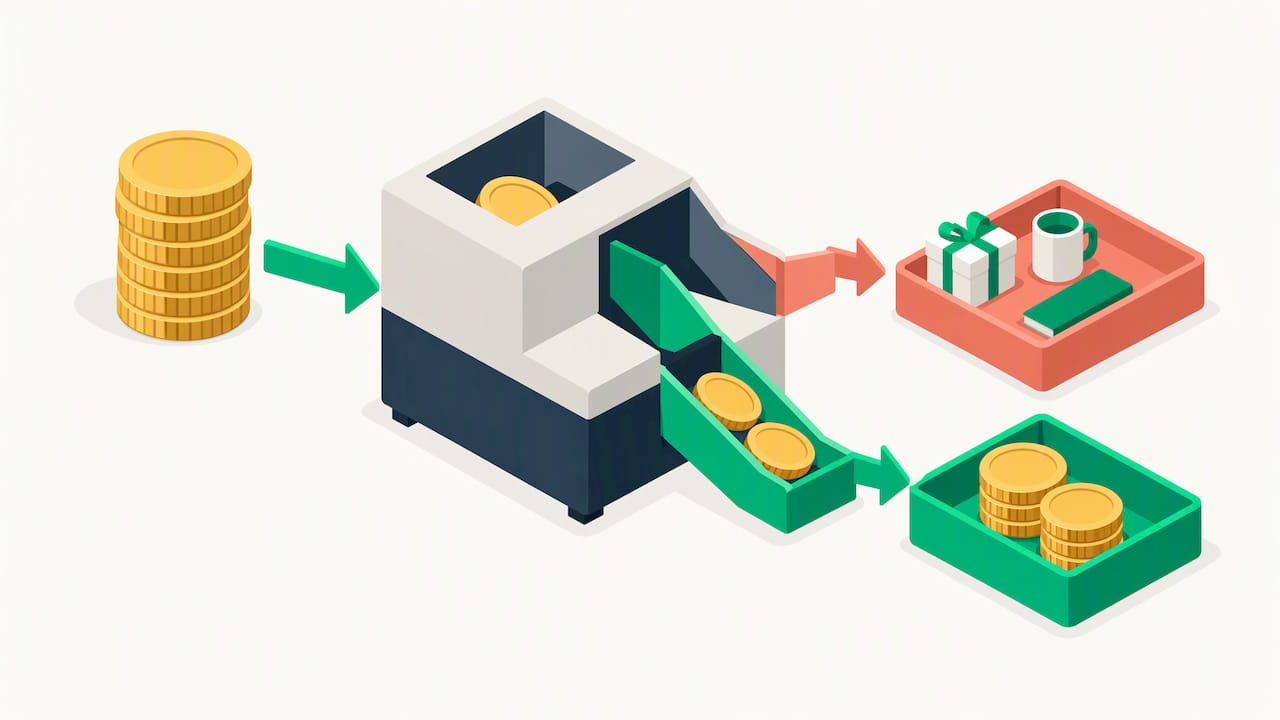
Minimum documentation looks the same on both sides of the transaction: a written acknowledgment for the donor, and a record of any FMV estimate for the charity, kept together with the original agreement.
Weighing visibility against tax simplicity
- Donations offer tax clarity and direct mission support, but they give a corporate giver little to show for brand visibility.
- Sponsorships offer marketing value and structured activation, but they carry more paperwork and a real risk of tipping into advertising, which complicates both the giver’s deduction and the nonprofit’s UBIT exposure.
- If the goal is pure mission support with a clean deduction, a donation is the simpler path.
- If the goal includes visibility or activation, a sponsorship can work, provided the agreement keeps promotional elements separate and priced.
How Charity Miles structures employer sponsorship around movement
Charity Miles’ Employee Empowerment program gives companies a working example of sponsorship built around employee activity rather than a single check. Employers choose the rate per mile, set a total sponsorship cap, and decide whether donations flow to each employee’s chosen charity or a company-selected cause, all through the Charity Miles app. The company controls how much visibility or acknowledgment it wants in the program, which keeps the sponsor’s role distinct from any promotional messaging aimed at employees.
- Employers can sponsor per-mile donations without directing employees to a single charity, preserving a donation-like structure for the underlying gift.
- Companies that want recognition can limit it to neutral acknowledgment, such as naming the challenge after the sponsor, rather than embedding calls to action.
- A team launched in 2021 saw a large increase in employee participation, with many employees generating a significant amount for charity.
Drafting notes matter here too: keeping sponsor acknowledgment separate from any promotional content, and documenting the fair market value of any branded materials, helps preserve the intended tax treatment on both sides.
Why the label on the check matters less than the deliverables
A contract’s deliverables control its tax treatment, not whatever word sits at the top of the page. You can call a payment a “sponsorship” and have it function as a donation for tax purposes, or call it a “donation” and have attached perks turn it into something else entirely. Watch for exclusivity clauses, marketing calls to action, and product endorsements baked into the agreement: any of those should prompt a conversation with a tax adviser before the payment goes out. Keep every acknowledgment letter, every fair market value estimate, and every version of the agreement itself, because that paper trail is what substantiates your position if the IRS ever asks.
— Gene
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What are the four types of sponsorships?
Sponsorship categories generally include cash sponsorships, in-kind sponsorships (goods or services instead of money), media sponsorships, and promotional or activation sponsorships that include marketing rights. The tax treatment of each depends on whether the agreement promises a substantial return benefit beyond simple acknowledgment, as described in the IRS sponsorship guidance.
What are the disadvantages of sponsorship?
Sponsorships carry more tax complexity than donations because promotional content can trigger unrelated business income tax for the nonprofit and reduce or eliminate the payer’s deduction. They also require more contract detail, since exclusivity, endorsements, and calls to action all shift the payment away from the sponsorship safe harbor described by the IRS.
How much of a sponsorship is tax-deductible?
A sponsorship payment is deductible only to the extent it exceeds the fair market value of any benefits the sponsor receives. Under the IRS quid-pro-quo rules, a $100 payment for a $40 benefit leaves $60 deductible, and the same subtraction applies to sponsorship perks like event tickets or premium signage.
What are the risks of sponsoring?
The main risk is reclassification: a sponsorship that includes promotional language, pricing claims, or exclusivity can lose its qualified-sponsorship status and become subject to UBIT for the nonprofit, per IRC §513(i). For the sponsor, that same shift can mean losing the deduction on part or all of the payment.
Is there a simple way to see this type of sponsorship model in practice?
Charity Miles’ Employee Empowerment program lets companies sponsor employee miles at a rate and cap they choose, directing donations to employee-selected or company-chosen charities. Companies interested in structuring their own program can review Corporate Sponsorship Opportunities to see how acknowledgment and activation options are kept separate.